Quick answer. A claim wants objects you would replace, not a postcard of the room. Each line names the thing the way a stranger would, says where it lives, and points at a photo of that object in place, the serial plate if it has one, and the receipt if you still have it. Build the list on a boring Tuesday. A camera roll is not the list.
What does a claim actually want from a home inventory?
You can name the TV. Maybe the couch. After that the list turns into a guess, and a guess is what a claim is bad at. The drill in the hall closet. The bikes on the garage wall. Last year's coat. None of that is the house. The house is the walls. The claim is the stuff.
Public checklists say the same thing without promising a dollar amount. The Insurance Information Institute tells people to photograph or videotape belongings, record serial numbers on major appliances and electronics, and keep receipts with the inventory — with a copy stored offsite. The NAIC home inventory page is built around room- or category-grouped photos you can export. After a disaster, the III's claims guidance asks for an inventory of damaged or destroyed items, receipt copies for the adjuster, and photos or video of the damage. That is paperwork help. It is not a payout formula. Policies differ.
What does a room photo fail to prove?
A panorama of the kitchen is a postcard. It proves a kitchen was in the frame. It does not name the soundbar behind the plant, the lamp you inherited, or the scratch already on the coffee table. An adjuster is not walking the house with you. They are looking at lines.
One object. One photo of that object where it lives. One photo of the plate or the receipt if it has one. The words you would use for a stranger. That is a line. A camera roll of birthday photos is not. For the camera-roll version of this job, see the photos that actually matter for a claim.
What belongs on a proof line, and what does not?
People treat four different things as if they were the same proof. They are not.
| What you have | What it can show | What it does not show |
|---|---|---|
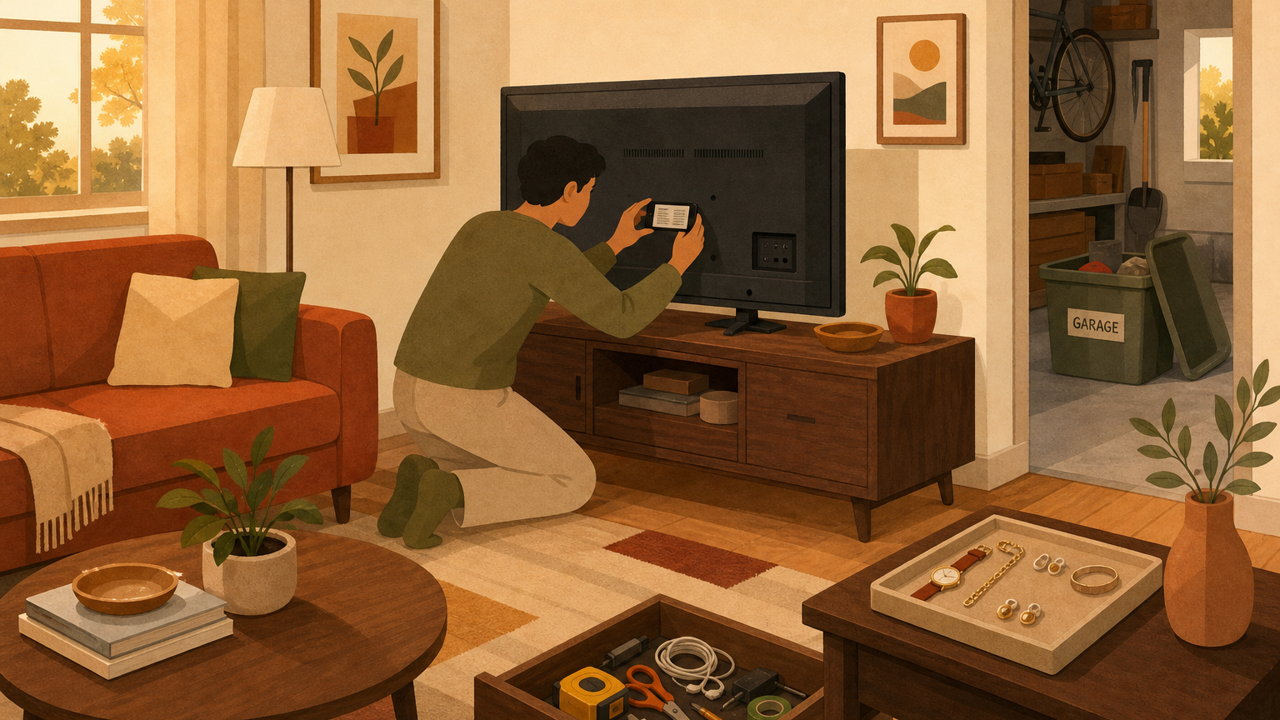
| Photo of the object, in the room | That this thing was there, in that spot, in that condition, the day you shot it | The serial, the price, or that you still own it later |
| Photo of the serial plate | Which unit it is, if the plate is readable and clearly the same object | That you bought it, or what you paid |
| Receipt | Who you paid, when, and how much, if it is for that object | That you still have it, or its condition now |
| A value you typed | A number you wrote down | What a policy pays. Policies differ. No formula on this page. |
Not every fork. The things you would replace, and the things you forget because they live in a closet. "Black cordless drill," not "tools." Hall closet, top shelf. Garage, left wall.
Where does a claim list go thin?
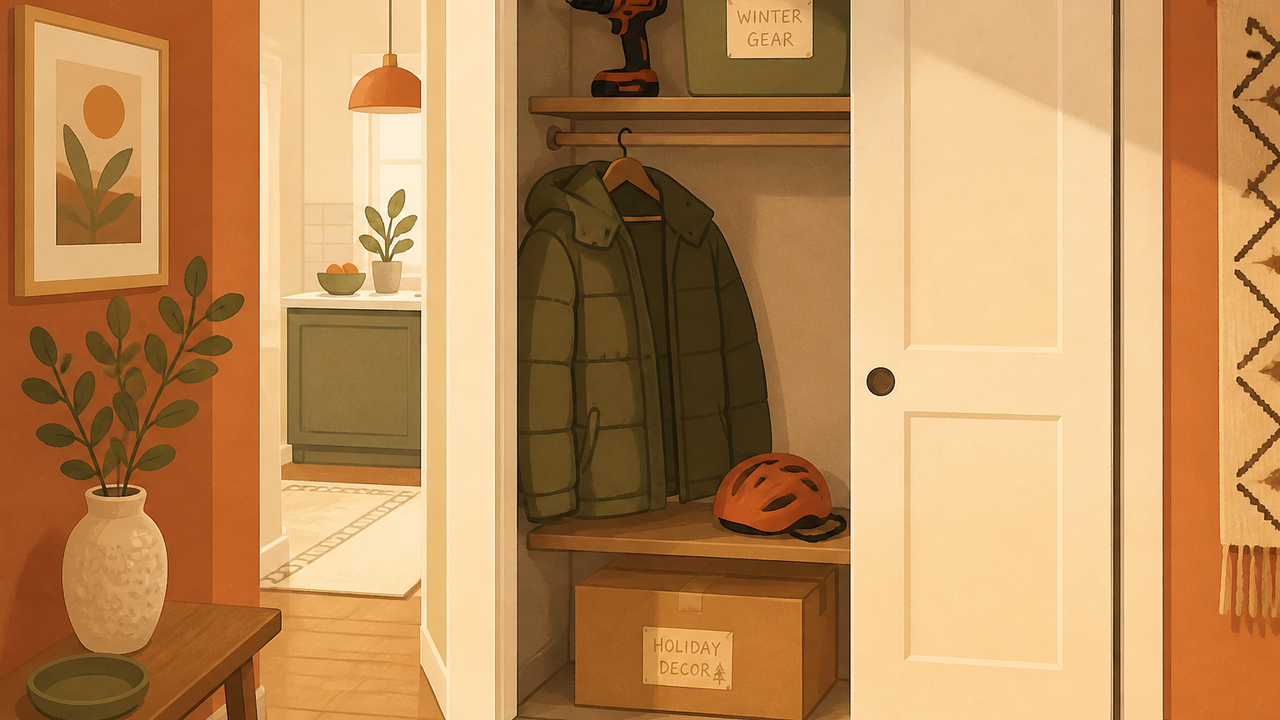
You remember the living room because you sit in it. You forget the hall closet because you open it with a purpose and close it again. That is where the winter coats, the camera bag, the spare monitor, and the good blender live. Walk the closets like they are rooms. Then the garage. Then the shed.
Tidy and findable are different. A bin labeled WINTER GEAR is tidy. "Green puffer, hall closet" is a line. The label on the bin is not. Same habit as listing furniture by room before a move: the photo has to name a thing, not a pile.
What should you do before a loss, not during one?
The worst week to start is the week you need the list. One room, then the closet next to it.
- Living room. The TV, the speakers, the furniture you would actually replace. Photo in place. Plate on the TV.
- The closet you use. Coats, bags, the box on the floor.
- Garage or basement. Bikes, mower, tools that cost more than you remember.
- Kitchen machines you would repurchase. The stand mixer. Not the spoons.
- Stop when you can say what you would list tomorrow without walking the house.
You do not need a weekend. You need the objects you stopped seeing.
What does the claim workflow look like after a loss?
Order of work — not a promise about money.
- Get safe. Do not enter a damaged structure to “finish the inventory” if it is unsafe. Ready.gov puts safety ahead of paperwork after a home fire.
- Notify the carrier the way the policy says. Ask what format they want for personal property.
- Pull the offsite copy of the list. Sort phone photos by room if that is all you have — do not invent names from memory first.
- If it is safe, photograph damage: wide, medium, close. Keep original files.
- Build lines from the proof matrix. Hand over copies. Keep your own set.
Honest limits: a neat list does not raise limits you never bought. Big-ticket jewelry, art, and collectibles may need to be scheduled — ask your agent before a loss. This page does not interpret your declarations page.
When is the list enough to hand over?
When a person who has never been in your house could act on a line without calling you. If a line still says "misc" or "stuff in the garage," it is not a line yet. The shorter lander version of this job is home inventory for insurance. Renters: the stuff is the same job, the building is not, on what to list on a renters claim.
If you want those photos to become lines without typing every one, that is what vorby.com is for. You still open the door. The app does not invent a drill you never photographed.
A few straight answers
What does a photo of a room fail to prove?
A wide shot shows a room was in the frame. It does not name the model, the serial, the price, or the object hiding behind the plant. A product photo from a store page shows even less. Photograph the thing where it lives, then the plate, so they are obviously the same object.
Do I need a line for every coffee mug?
No. Everyday dishes can stay one line. Give a line to the mug you would actually replace, and to the things you forget because they live in a closet.
Is a video walkthrough enough for a claim?
A walkthrough is a moving room photo. It is a start. Pause and shoot the object, then the plate if it has one. The claim is a list, not a tour.
How detailed does the list need to be?
Detailed enough that someone who has never been in your house could act on the line without calling you. Black cordless drill, hall closet, top shelf is a line. Tools is not. Policies differ. This page does not invent a carrier rule.
What should I do right after a loss?
Get safe, call the carrier, pull the offsite list, photograph damage only if the building is safe, and build lines from photos, serials, and receipts. Keep copies. An inventory helps the claim file. It does not invent coverage.
What if I rent?
The job is the same for your stuff. The building is a different policy. What to list on a renters claim is the longer page.