Renewal asks you to pick a number for your belongings. We gathered the rules of thumb, the hidden caps and a worksheet so you can check that number against a real total.
This is general information, not insurance advice; limits and sublimits vary by insurer, policy form and state, so check your declarations page and ask your agent.
How much personal property coverage do I need?
Enough to replace everything you own at today's prices. Homeowners policies often set personal property at 50 percent of the dwelling limit, and insurers cite 50 to 70 percent as a rule of thumb. Renters pick their own limit, often $20,000 to $50,000. A room-by-room inventory total is the number to check against.
- NAIC: personal property at 50 percent of the dwelling limit, so a $150,000 dwelling gives $75,000.
- Insurance Information Institute (III): about 50 to 70 percent of the dwelling insurance.
- Travelers: 50 to 70 percent, and renters limits typically $20,000 to $50,000.
- California Department of Insurance: generally around 50 percent, "a guideline only".
Is 50 percent of dwelling coverage enough for my belongings?
Only if your inventory total is below it. The percentage comes from the policy form, not from your house, so a family with a full garage, home office or collections can exceed it. Add up replacement costs room by room, compare the total with your personal property limit, and ask your agent to raise the limit if you are short.
California's department says "the most reliable source of information on the replacement value of your personal possessions is you" (CDI). NAIC adds: "Check your policy" (NAIC). For the basics, see our guide to dwelling vs personal property coverage.
How do I add up the value of my belongings?
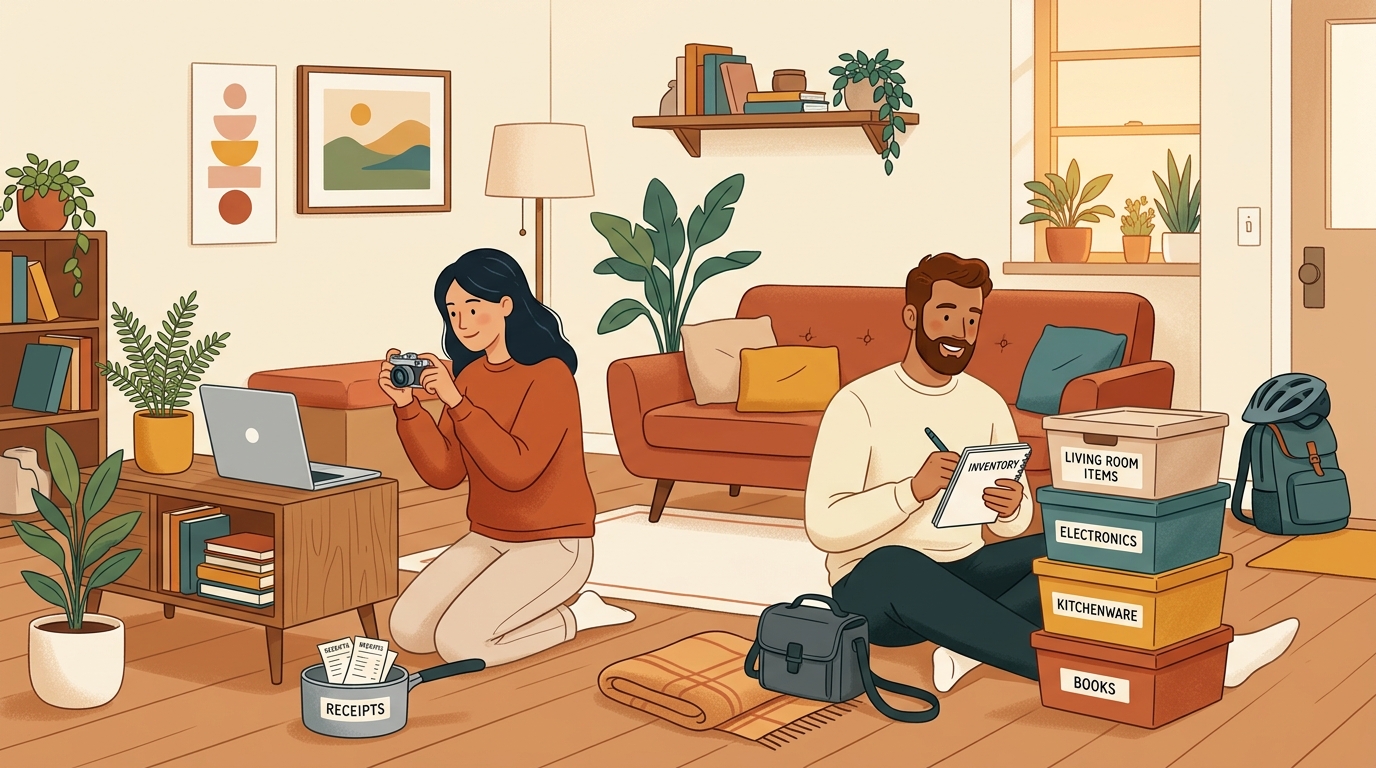
Go room by room, including the garage, closets, attic and any storage unit. For each item, write what it would cost to buy new today, not what you paid. Group small things by category, list valuable items one by one, and total each room. Round up, and redo the total after big purchases or gifts.
Use categories so nothing slips through. GEICO's calculator groups belongings into furniture, appliances, decor, dishes and cookware, linens, clothing, computers, electronics, media, cameras, fitness gear, outdoor equipment, tools, jewelry and watches, and other. Then check the places people forget:
- Under beds and in the coat closet
- Garage shelves and the shed
- The attic and the basement
- Off-site storage units
- Anything lent out
Which belongings have their own lower limits?
Standard homeowners policies cap some categories well below your overall limit. New York's Department of Financial Services lists typical caps such as $1,500 for theft of jewelry, watches and furs, $2,500 for theft of guns or silverware, $200 for money, and $2,500 for business property at home. Your policy may differ.
Source: New York DFS. The III also puts jewelry theft at generally about $1,500. Fill in the worksheet with your own totals.
| Category | Your inventory total (replacement cost) | Typical limit | Gap | What to ask your agent |
|---|---|---|---|---|
| All belongings | $214,000 | $200,000 personal property | $14,000 short | Raise the personal property limit |
| Jewelry and watches (theft) | $9,800 | $1,500 | $8,300 short | Schedule the ring and watch after an appraisal |
| Guns (theft) | $3,100 | $2,500 | $600 short | Raise the special limit or schedule |
| Silverware (theft) | $1,200 | $2,500 | None | Nothing |
| Home office business gear | $4,400 | $2,500 on premises | $1,900 short | Ask how to cover business property at home |
| Cash | $350 | $200 | $150 short | Keep less cash at home |
| Bikes, golf clubs, instruments | $5,600 | No special limit listed by NY DFS | Check your policy | Ask whether your insurer caps these |
Values are illustrative only. Here is a blank version to copy:
| Category | Your inventory total (replacement cost) | Typical limit | Gap | What to ask your agent |
|---|---|---|---|---|
If a category comes up short, the III describes two fixes:
- Raise the special limit. III's example is a limit of $2,000 per piece with $5,000 overall.
- Schedule the item on a floater. The item must be professionally appraised first.
NAIC calls the second option a scheduled personal property endorsement, or "personal article floater".
Should I insure belongings at replacement cost or actual cash value?
Replacement cost pays to buy a new equivalent. Actual cash value subtracts depreciation, so an older sofa pays out far less than a new one costs. III says replacement cost coverage for homeowners costs about 10 percent more and is generally worth it. Whichever you choose, size your limit from replacement prices, since that is what you would spend.
Source: III. For the longer explanation, see our homeowners guide.
Does flood insurance cover my belongings?
Not under a standard homeowners or renters policy. Contents flood coverage is a separate NFIP policy that covers up to $100,000 of belongings, and III notes it pays actual cash value. FEMA's FloodSmart site also says items in basements are generally not covered, so a basement full of stored things needs a different plan.
Sources: FloodSmart and III. If water has already come in, see our list for what to record after a flood.
Keeping the total current
In Vorby, one photo can detect several items, so a shelf becomes a list quickly. Each item can carry an estimated value, including on the free plan, and each room, each location and the house page show a total of those estimates. Treat that total as a starting point, not an appraisal, and price anything valuable yourself before you set your limit.
Use labels such as "Jewelry", "Schedule this" and "Business gear" to match the worksheet rows. A label page lists its items and shows how many there are, but not a value total. Attach receipts and appraisals to items. Before you meet your agent, export the list as CSV or Excel. Each row includes labels, price and estimated value, so you can total each worksheet category in a spreadsheet.
Renting? Our renters insurance inventory guide covers the same steps for a tenant.
Photograph each room once, add estimated values, and Vorby keeps a running estimated total for every room and the whole house, so you can check it against your policy before renewal.
Get Vorby on the App Store or Start your inventory on the web.
Frequently asked questions
How much personal property coverage do renters need?
Renters choose their own limit, so start from an inventory total rather than a guess. Travelers says typical renters limits range from $20,000 to $50,000, but your number depends on what you own and what it would cost to replace. Add up each room at today's prices, then pick a limit at or above that total.
What is Coverage C on a homeowners policy?
Coverage C is the personal property part of a standard homeowners policy: furniture, clothing, electronics and other belongings you could move. On many policies it is set as a percentage of the dwelling limit, which NAIC lists as typically 50 percent. Some categories, such as jewelry theft, carry lower special limits inside it.
Can I increase my personal property coverage?
Usually, yes. Ask your agent or insurer to raise the personal property limit if your inventory total is higher than it. For valuables above a special limit, III describes two options: raise that special limit, or schedule items on a floater after a professional appraisal. Floaters can also cover accidental loss, which standard policies may not.
How often should I update my home inventory total?
NAIC recommends reviewing and updating your home inventory every year and whenever you buy new items. A good habit is to check the total before each policy renewal and after holidays, birthdays or a big purchase such as a laptop or furniture, so the limit you choose still matches what you own.